Your Raise Dies at 51.5 Hours
Your raise dies at about 51.5 hours a week. That is when the median computer and information systems manager, at $175,140 a year, drops back to the $65.38…
51.5 hours a week — where the median raise dies
Chronological Archive
Newest first, across 4 decision areas. Every article is a full breakdown of the maths behind one decision — no summaries you have to take on faith.
Showing all 27 articles.
Your raise dies at about 51.5 hours a week. That is when the median computer and information systems manager, at $175,140 a year, drops back to the $65.38…
51.5 hours a week — where the median raise dies
Your equity payday at an initial public offering (IPO) is mostly a tax bill. One filing this month put a 47.7% number on it.
Moving abroad adds three required US forms, and missing just one costs $10,000. Not one of these forms bills you for tax.
An hour of network admin work was worth $47.66 at the 2025 median wage. A year of managed email costs $60.
1.26 hours of upkeep a year before a $5/mo plan wins
The maker of Home Assistant announced a rename of its paid remote service, effective December 2. Home Assistant Cloud becomes Home Assistant Link.
SpaceX workers get their next chance to sell today as 328.4 million shares — about 7% of the locked stock — open for trading.
Three months after a job ends, an incentive stock option loses its tax status — the alternative minimum tax on the exercise spread can outweigh the strike.
Two clocks dictate the true cost of moving abroad, and they rarely sync up: the US demands 330 full days overseas within a 12-month window to shield your…
On Sept. 23, Disney+ and Hulu pushed their ad-free streaming plans up 13 percent to $21.49 a month. This marks the fourth price hike in four years.
More than 70% of vested startup stock options are never exercised, according to new data from Carta published Sept. 10.
For mid-career professionals, moving abroad is no longer a simple salary comparison. Expats must weigh a U.S. $200K tech salary against a €130K European offer, then factor in lower healthcare, education, and daily costs alongside dual-country taxation expats face, visa rules, and hidden relocation expenses. This guide cuts through the noise with a practical framework for expats Costa Rica, expats Germany, and other markets, helping you answer the critical question: is relocating for a job worth it? You will learn how to calculate true net cash flow, anticipate cross-border tax liabilities, and score cities on livability, career momentum, partner employment, schools, and community. The Expat Financial & International Tax Evaluator turns guesswork into a clear, personalized decision. Before you accept the offer, run the numbers, test the lifestyle trade-offs, and protect your long-term wealth. Your next move deserves evidence, not hope.
For many coffee enthusiasts, the decision to invest in a premium espresso maker machine is clouded by emotion and brand loyalty. A data-driven approach, however, reveals a surprising bottom line. Using the Giniloh Strategic Decision-Intelligence Engine, a detailed cost-per-use analysis of a $3,000 dual-boiler home espresso machine versus daily $6.00 café lattes yields a clear verdict: buy the machine—but only just. Over three years of five weekly drinks, the home setup costs $5.92 per use, saving a mere $60 compared to the café’s $4,680 total. Hidden expenses like beans, milk, descaling, and maintenance push the total cost of ownership to $4,620, making this a borderline decision. The real value emerges when weekly usage increases, tipping the scales toward significant long-term savings. Before you swipe your card, run your own numbers: the difference between a rational investment and a costly impulse is just one calculation away.
Imagine your checking account drops to $500 after an unexpected car repair—but within hours, an automatic sweep from your savings restores your floor, no manual intervention required. That’s the power of the Giniloh Frictionless Money Flow Simulator, a hands-on tool that lets you practice real-life financial shocks in a risk-free environment. The emergency expense scenario, a core feature, demonstrates how setting a $1,500 checking floor paired with a $15,000 high-yield savings account triggers an automated rescue when an unplanned bill hits. You can run the simulation yourself using AI chat commands or manual UI configuration, then watch the cyan flow path and audit trail log confirm every transfer. This isn’t static advice—it’s a live, repeatable drill that trains your system to protect against financial shocks and avoid high-interest debt, giving you confidence when real emergencies strike.
Let’s cut to the chase: a liquidity sweep isn’t just random market noise—it’s where institutional players deliberately spike prices through stop-loss clusters to grab trapped liquidity. If you’ve ever watched your stop get hit only for the market to reverse immediately, you’ve seen one. Most traders never learn to spot them, let alone simulate scenarios before risking real capital. That’s where this guide changes everything. You’ll not only learn how to identify buy-side and sell-side sweeps using swing highs and lows, but you’ll also get hands-on with the Giniloh Frictionless Money Flow Simulator—a tool that lets you configure accounts, set up automated cash pipelines via natural language CLI, and step through daily clocks to watch sweeps unfold in real time. No more guessing. By the end, you’ll have a repeatable, actionable framework to anticipate liquidity grabs and safeguard your positions.
Imagine your income suddenly surges to $500 a day, your emergency fund is fully stocked at $15,000, and you carry zero high-interest debt. Where does every extra dollar go? The giniloh Money Flow Simulator answers that question with stunning clarity, turning abstract financial planning into a visual, real-time cascade. By simply setting your income and account ceilings—via an AI chat command or a few clicks—you watch surplus cash automatically bypass saturated reserves and flow into tax-advantaged accounts like your 401k, HSA, and Roth IRA. The true power emerges when these hit their annual limits; then, without any manual intervention, every remaining dollar dynamically overflows into a taxable brokerage account. With an audit trail logging each “overbalance sweep,” this simulation transforms a theoretical pay raise into a specific, actionable roadmap for wealth acceleration. It’s not just a chart—it’s a live demonstration of how to make every surge work harder, before you ever see a real paycheck.
Worried robots are coming for your paycheck? You’re not alone—but the real story is far more hopeful. This guide cuts through the scare headlines to reveal exactly where smart, sustainable career opportunities exist right now. We’ve curated a list of true ai proof jobs—roles in healthcare, skilled trades, and cybersecurity that not only survive automation but thrive because of human judgment and empathy. You’ll get specific, money-making data on projected growth (the BLS says wind turbine technicians, for instance, will grow 44% by 2032), real salary ranges from active job listings, and a simple self-assessment quiz to identify your own most resilient path. Plus, we name companies hiring today and the niche job boards they use. Stop worrying and start planning—your secure career is closer than you think.
For professionals weighing a leap into Nvidia’s RTX PRO lineup—a $12,400 Blackwell 6000 with 98GB VRAM—the sticker shock often overshadows long-term value. But what if a single interactive calculator could reveal whether that investment pays off faster than renting cloud GPUs? Gilinho’s new TCO Analyzer does exactly that, letting you input acquisition cost, power draw, maintenance, and depreciation to compare ownership versus rental across workloads like Llama 3 inference or Blender rendering. Early results show the RTX PRO can slash cost per render hour by 40% over a three-year horizon. Stop guessing and start optimizing your hardware budget. Try the analyzer now to see if RTX PRO is your smartest compute bet.
Sarah faced a classic career-versus-home dilemma: a $20,000 salary bump in NYC, but eight months and $24,000 remaining on her Austin lease. With confusing penalty clauses and no clear exit path, she needed hard numbers—not guesswork. Using the Giniloh Lease Break Calculator, she compared three real scenarios: a worst-case $3,500 outlay, a negotiated buyout at $1,650 net, and a best-case where her new employer covered the exit cost. The calculator’s payback math revealed she’d fully recover even the worst penalty in just 2.1 months. Armed with concrete data, Sarah turned a painful lease break into a leverage point—either for a signing bonus or a swift financial recovery. The result? A clear, data-driven path out of a costly commitment, proving that with the right tool, breaking a lease doesn’t have to break your budget.
E-commerce teams relying on a zapier notion integration to sync customer data and orders often face a hidden cost far exceeding any subscription fee. When broken integrations, duplicated records, and sync timeouts consume 12 hours of an operations manager’s time each month at $85 per hour, the monthly tinkering tax hits $1,020. That’s $36,720 over three years—more than double the $18,000 premium for upgrading to a unified centralized CRM like HubSpot. By plugging these real-world figures into Giniloh’s No-Code Workaround Terminator calculator, you can see the exact net savings—$18,720 in this scenario—and reclaim stress-free operations. Stop guessing whether your workflow is worth it; the data reveals the smarter move.
Is a cracked laptop screen forcing you to shell out hundreds for a repair? Before you rush to replace laptop screen, stop and calculate whether it's actually worth it. Most repair guides only show you how, not if you should. That's where the Giniloh Strategic Decision-Intelligence Engine changes the game. Instead of guessing, use the Consumer 1,500 Rule: multiply your laptop's age by the repair quote. If the result exceeds 1,500, it's smarter to buy new laptop than patch old hardware. A 4-year-old device with a $450 repair gives you an asset tech debt index of 1,800—a clear "replace" verdict. This data-driven approach saves you from pouring money into outdated machines. Learn the exact steps to perform the calculation, get a definitive answer, and stop wasting funds on uneconomical fixes. The math doesn't lie—your wallet will thank you.
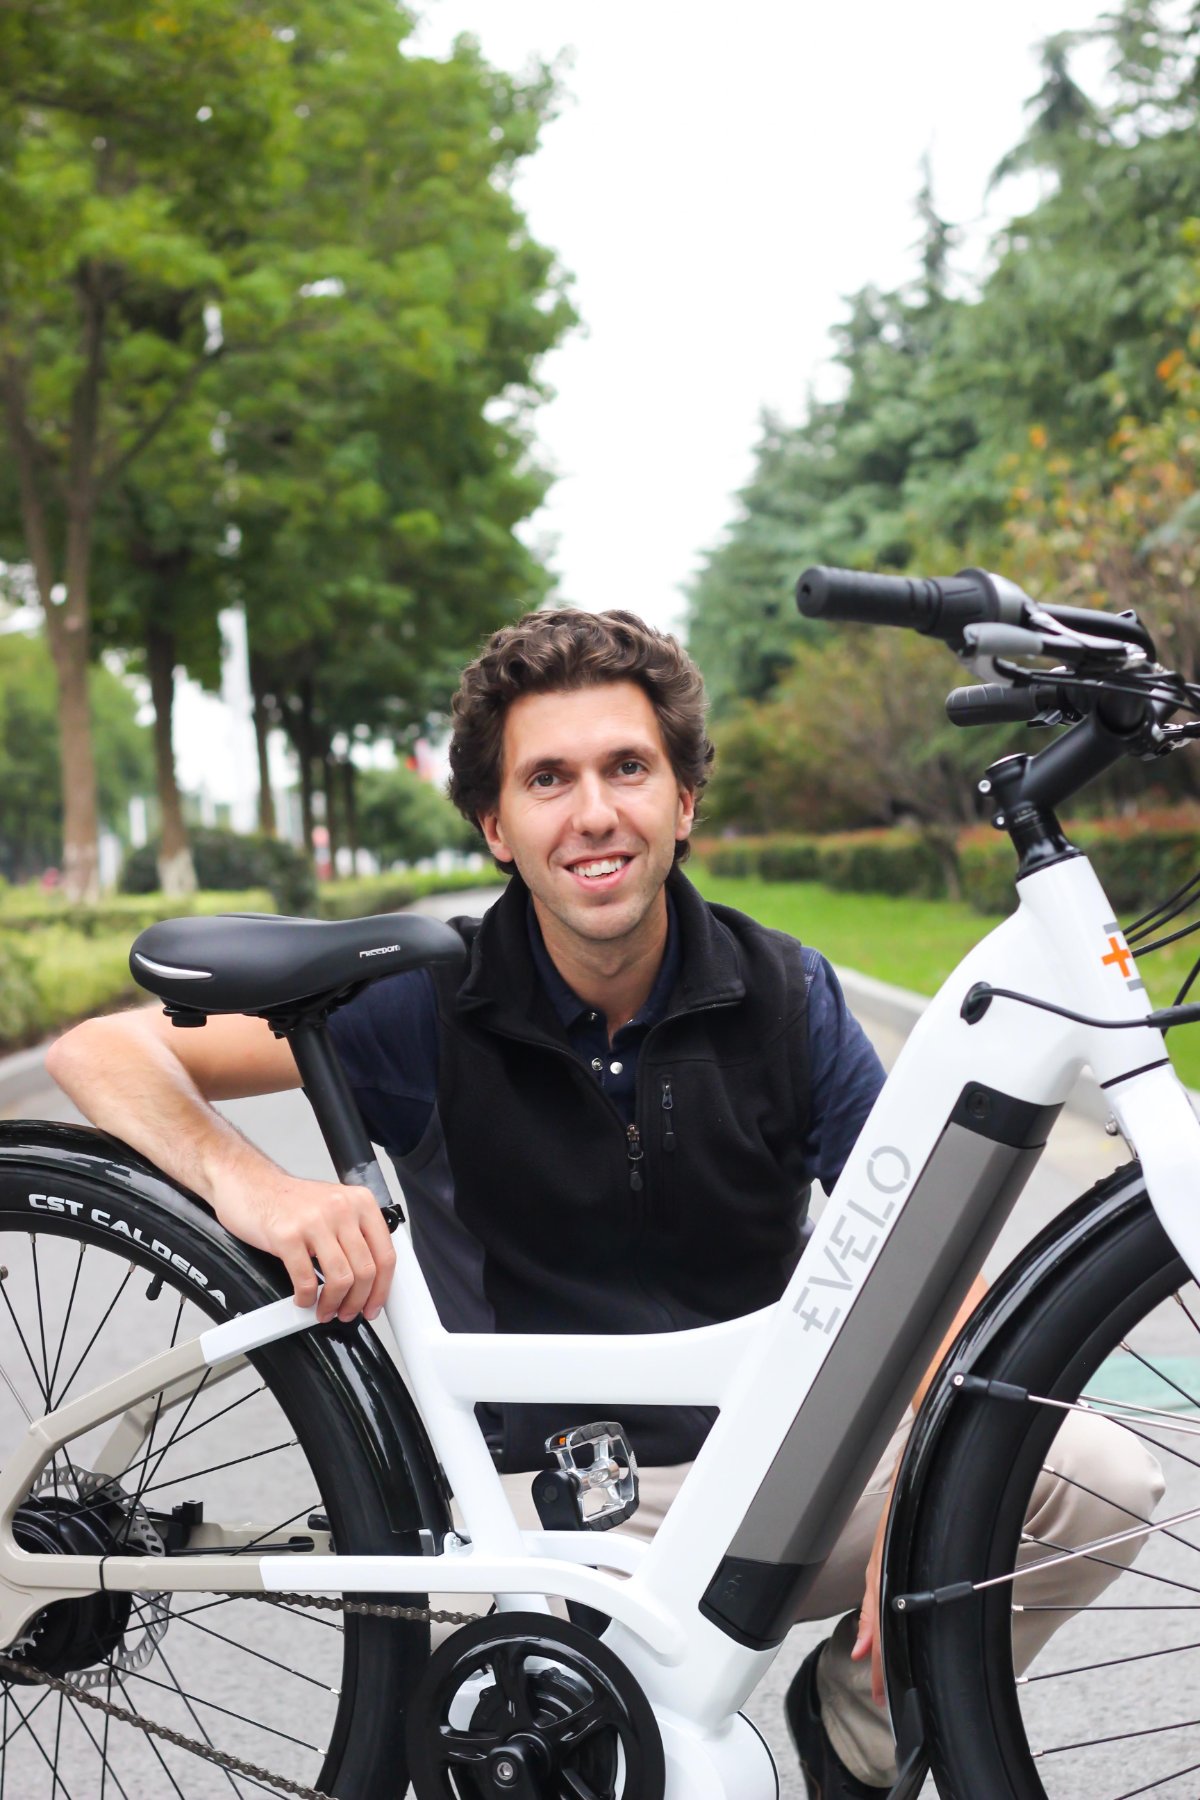
Stop guessing whether an e-bike is worth it—most people overpay for their commute without realizing it. This article uses the Giniloh Decision Intelligence Framework to uncover the true ebike costs and which choice saves real money. Instead of just listing price tags, you’ll learn a simple Cost-Per-Use (CPU) calculation that compares a $2,500 premium e-bike against your current parking, fuel, and rideshare expenses. The result? A commuter who rides three days a week could save $2,875 over three years—dropping their per-trip cost from $15.00 to just $7.90. That’s a clear BUY verdict based on your own numbers. By matching the electric bike cost to your exact lifestyle, you stop overthinking and start saving immediately. Ready to run your own CPU check? The interactive calculator inside does the math for you.
Are you considering a jobs switch but worried about forfeiting years of unvested 401(k) matches? The Gilinoh Raise & Job-Hop Velocity Calculator exposes the hidden financial trade-offs most professionals overlook. In a realistic scenario, a mid-career engineer earning $120,000 receives a 12% raise offer—yet loses over $21,000 in unvested employer matches, creating a $4,000 switching deficit in year three. This tool transforms abstract risk into concrete numbers, showing exactly how to negotiate a signing bonus of at least $15,000 to break even. Stop leaving money behind. Use the calculator’s step-by-step walkthrough to compare stay-versus-switch trajectories, identify negotiation levers, and ensure your next move actually pays off.
Moving for a career relocation is one of the most consequential financial decisions a professional can make—yet most job offers gloss over the hidden costs that can turn a salary bump into a net loss. A new interactive tool, the Giniloh Career Relocation Cost & Payback Calculator, changes that by delivering hard numbers instead of guesswork. In a real-world case study—a software engineer leapfrogging from Maryland to California for a $25,000 raise—the calculator reveals a net upfront cost of $6,065 driven by lease penalties and an overlooked state-tax drag on employer reimbursements. More importantly, it pinpoints the exact break-even point: just 5.0 months, after which the move becomes pure profit. By modeling taxable transit benefits, AB 692 exclusions, and monthly take-home gains, this calculator transforms career relocation from a leap of faith into a data-backed strategy. Don’t sign that offer without knowing your actual payback timeline.
Most candidates fixate on base salary when they negotiate a job offer—but that leaves money on the table. The Giniloh Total Compensation Visualizer transforms the process. You input specific numbers for salary, equity, bonuses, and benefits, then instantly see how different scenarios affect your net worth. Simulate asking for higher salary versus more equity and compare long-term outcomes. This visual representation gives you objective data to justify counteroffers with confidence. Don't accept a deal that undervalues your skills. Before your next call, prepare a TCV visualization to highlight gaps and trade-offs. Discover a step-by-step method to quantitatively compare offers and turn a stressful conversation into a strategic advantage. Learn how to use this tool to negotiate a job offer that reflects your total value and secure the package you deserve.
Imagine taking control of your money flow without the usual spreadsheet headaches or second-guessing every move. That’s exactly what the Giniloh Money Flow Simulator delivers—a risk-free sandbox where you can test your smart money decisions in real time. Instead of hoping your bills line up, you automate cash flow pipelines that sweep surpluses toward debt, savings, or investments while underbalance pulls instantly prevent overdrafts. No more panic, no more guesswork. Based on the Loh-Friction Philosophy, this tool lets you simulate aggressive paydowns, emergency floors, even corporate treasury sweeps, and watch exactly how your money decisions play out before committing a single dollar. With built-in regulatory guardrails like Roth IRA penalty checks, the model stays realistic. Stop leaving your financial momentum on idle—start testing your strategies today and see your money flow work for you.
Mastering your money flows is no longer guesswork. The Giniloh Frictionless Money Flow Simulator lets you configure a real-time cash routing engine on an interactive canvas—click any account node to drag sliders for balances, ceiling limits, and safety floors. Its AI Orchestration Chat establishes automated pipelines, then tests them against macroeconomic scenarios like stagflation or a 2008-style market contraction. You can apply conditional market scripting rules that adjust sweeps when inflation rises or buy dips when the S&P 500 drops. The simulator enforces regulatory guardrails—blocking Roth IRA early withdrawals, settlement delays, and pattern-day-trader limits—so every simulation mirrors reality. Start the automated clock or step day-by-day to watch your cash move according to your logic. Whether in Personal or Enterprise mode, this tool transforms abstract financial planning into a concrete, risk-free sandbox. Stop guessing; start controlling where your money flows before it hits the real world.
Imagine taking control of your money flow without the usual stress of spreadsheets or guesswork. Our Frictionless Money Flow Simulator changes everything by letting you visualize and test automated cash flow pipelines in real time—before you commit a single dollar. Based on the Loh-Friction Philosophy, it eliminates decision fatigue: surpluses automatically sweep toward debt, savings, or investments, while underbalance pulls instantly retrieve funds to prevent overdrafts. No more manual juggling or retrospective panic. You can simulate real-life scenarios—aggressive debt paydown, emergency floor protection, even corporate treasury sweeps—and see exactly how your smart money decisions play out. With built-in regulatory guardrails (like Roth IRA sweep penalties), the model stays realistic. Start testing your strategies today and stop leaving your momentum on idle.
Browse by topic
Navigate technological disruption with hard metrics. Evaluate whether to adopt, pivot, or bypass AI tools and workflow shifts to protect your income and operational efficiency.
Subcategories
Practical guides for deciding whether something is worth buying, upgrading, repairing, replacing, or skipping. This section focuses on real-world tradeoffs like cheap vs expensive, premium vs budget, cost-per-use, hidden costs, and when “better” is actually worth paying for.
Mental models and economic formulas to eliminate bias, calculate opportunity cost, and make objective choices.
Clear decision guides for everyday personal finance choices: saving, spending, debt, subscriptions, emergency funds, budgeting, and tradeoffs that affect your cash flow. The goal is not abstract financial advice, but helping you make better money decisions with the numbers and context you already have.